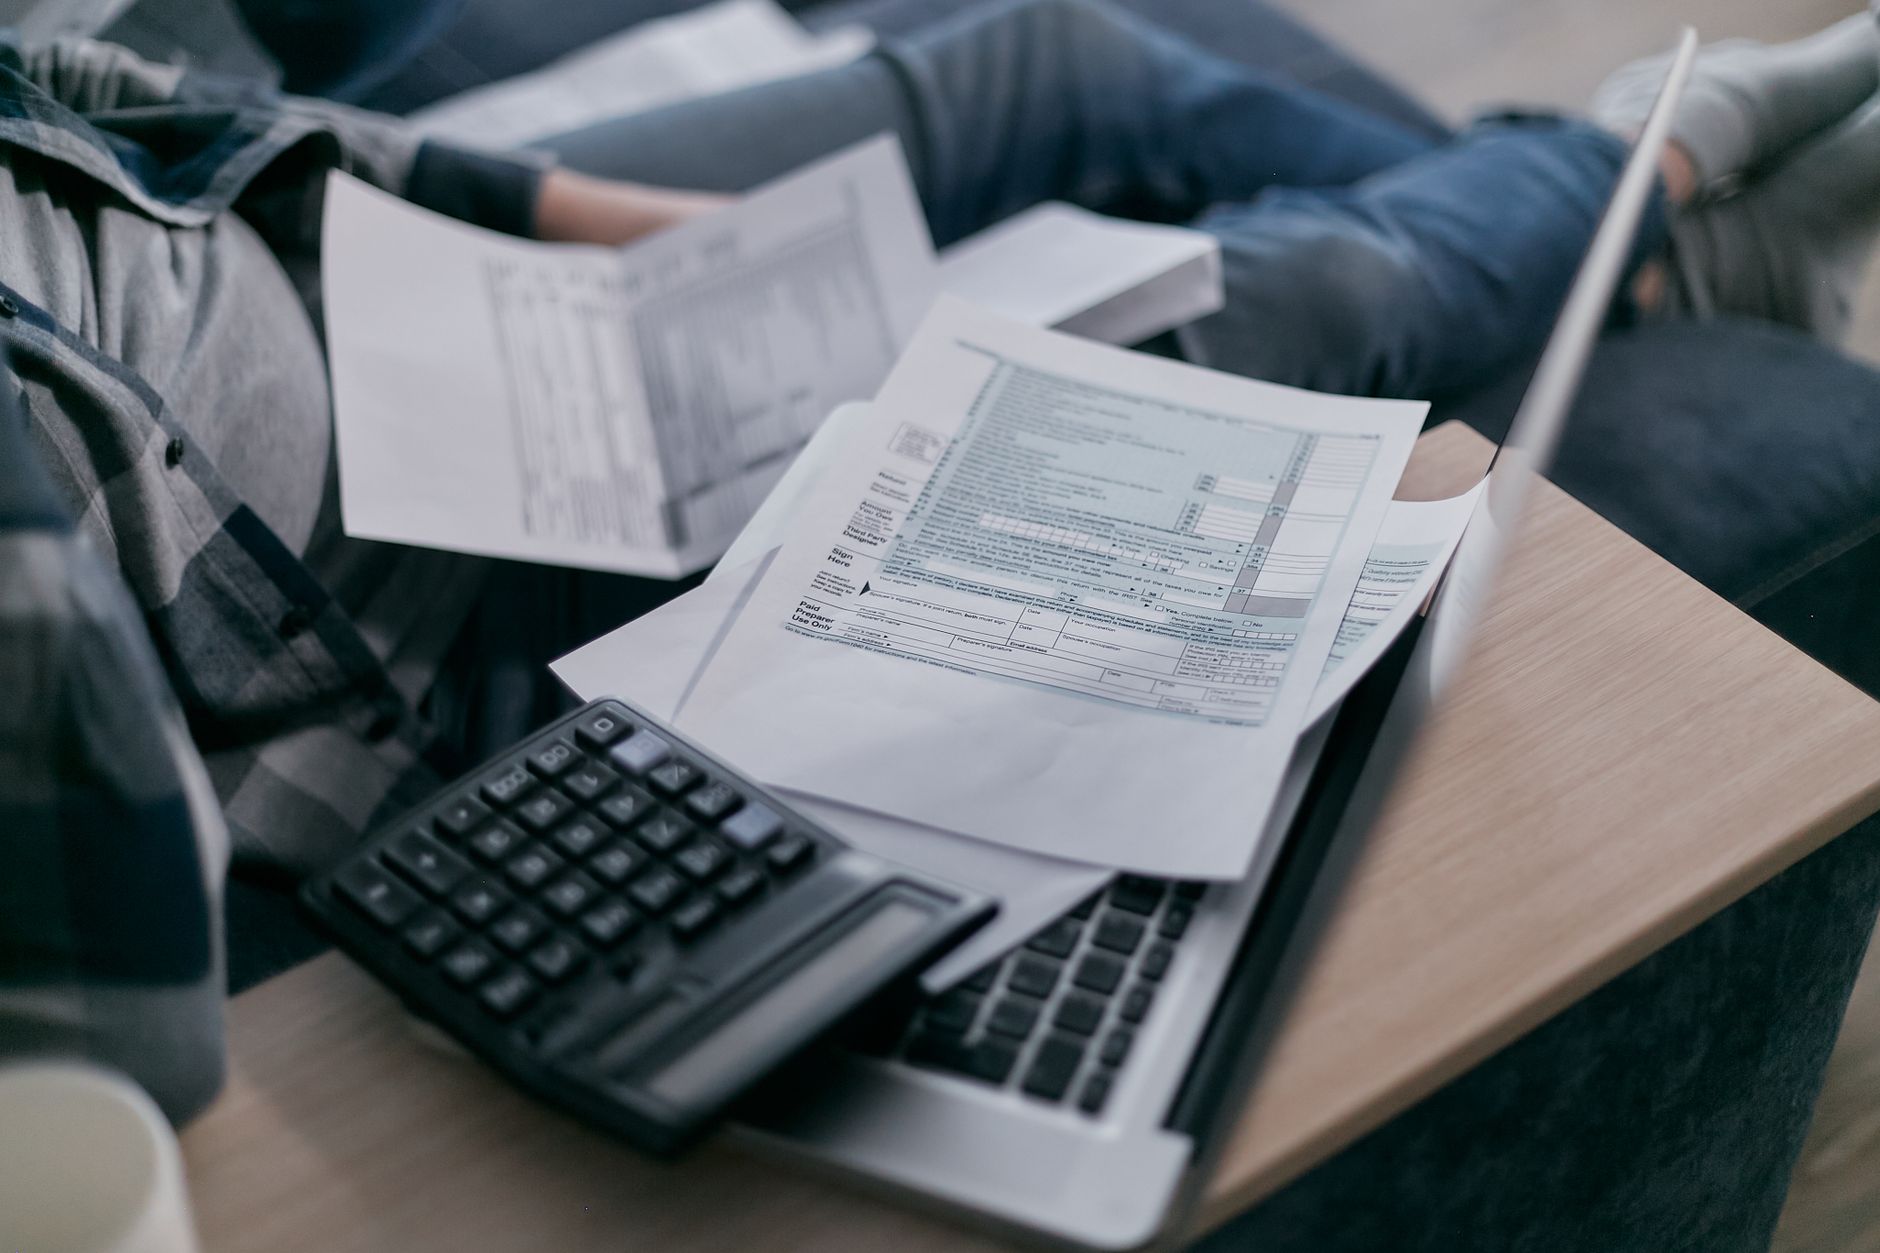
Taxpayers are legally required to report all cryptocurrency and digital asset activity on their federal tax returns. Because the IRS classifies cryptocurrency as property rather than fiat currency, transactions are subject to specific capital gains and income tax regulations.
Navigating crypto tax statements requires a clear understanding of your platform documents, cost basis tracking, and the appropriate IRS reporting schedules. Below is a breakdown of what you need to know to stay compliant.
Understanding Taxable Crypto Transactions
Filing accurate crypto taxes begins with identifying which transactions are taxable. Many users mistakenly believe that taxable events only occur when converting digital assets back into cash. However, the IRS outlines several common actions that trigger tax liabilities:
- Selling cryptocurrency for fiat currency (USD, EUR, etc.)
- Trading one cryptocurrency for another (such as swapping Bitcoin for Ethereum)
- Using cryptocurrency to purchase goods or services
- Earning crypto through staking, mining, airdrops, or platform rewards
When you earn crypto through staking or rewards, the value at the time of receipt is treated as ordinary income. If that same asset appreciates and you later sell it, you will also incur a capital gain on the subsequent profit.
Key Crypto Tax Documents and Statements
To accurately file your taxes, you must gather transaction records and statements from the digital asset exchanges, wallets, and brokers you used throughout the year. Major platforms provide specific documentation to assist with this process.
Exchanges like Coinbase are required to issue a Form 1099-MISC if you earned more than $600 in crypto rewards or staking income. Even if you earn below this threshold, you are still obligated to report the income. Additionally, platforms like PayPal supply a comprehensive transactions summary and a year-end gain/loss statement. These documents include crucial cost basis information for assets bought and sold on the platform, mirroring the data required for IRS reporting.
| Form or Schedule | Who Should File | What to Report |
|---|---|---|
| Form 8949 | Anyone with capital gains or losses from crypto | Details of each crypto disposal, proceeds, and cost basis |
| Schedule D | Anyone reporting capital gains or losses | Net gain or loss from crypto calculated on Form 8949 |
| Schedule 1 | Anyone who earned ordinary income from crypto | Staking, mining, or reward income reported as additional income |
How to File Using Form 8949 and Schedule D
When you dispose of a digital asset, you must calculate your capital gain or loss. This requires knowing the description of the asset, the date you acquired it, the date of disposal, your proceeds in USD, and your cost basis.
Short-term capital gains apply to assets held for one year or less, which are typically taxed at standard income tax rates. Long-term capital gains apply to assets held for more than one year and usually benefit from lower tax rates. Once you calculate these figures, you must report them on Form 8949 (Sales and Other Dispositions of Capital Assets) and then transfer the totals to Schedule D (Form 1040).
Many investors utilize specialized crypto tax software or services to automatically generate a Form 8949. Tax preparation software, such as FreeTaxUSA, allows you to enter your total long-term and short-term sales summary and attach your generated crypto Form 8949 directly to your electronic tax return. Regardless of whether you used digital assets during the year, remember that every tax filer must check the mandatory "Yes" or "No" digital asset box on their Form 1040.
Frequently Asked Questions
What is the main difference between how the IRS taxes crypto income versus capital gains?
Crypto income is taxed as ordinary income based on the fair market value when you receive it, such as from staking or mining. Capital gains are triggered when you sell, trade, or dispose of a digital asset, and the tax rate depends on whether you held the asset for a year or less (short-term) or longer than one year (long-term).
Do I need to report crypto activity if I only lost money this year?
Yes, you are still required to report your digital asset activity. Capital losses can actually be used to offset capital gains and up to $3,000 of ordinary income, making accurate reporting vital even during market downturns.
What forms will I receive from platforms like Coinbase and PayPal?
Depending on your activity, you may receive a Form 1099-MISC if you earned over $600 in staking or rewards income. Platforms like PayPal and Coinbase also supply transactional summaries and year-end gain/loss statements containing cost basis information to help you complete Form 8949.
References & Sources
- How do I file my taxes for cryptocurrency?
- Tax forms, explained: A guide to U.S. tax forms and crypto reports
- Crypto Tax Software - Report Investments on Your Taxes | FreeTaxUSA®
- Taxpayers need to report crypto, other digital asset transactions on their tax return | Internal Revenue Service
- Crypto Tax Forms: What You Need for 2026 | CoinLedger
Editorial Note: This article was researched via verified live web sources and published on 2026-11-15. Questions or feedback? Contact the editorial staff at TrendsInNews.
Photo credit: Mikhail Nilov / Pexels