When selling, swapping, or spending cryptocurrency, any profit you make is generally treated as a taxable event subject to capital gains or ordinary income taxes. Understanding your holding periods, cost basis, and specific disposal triggers is essential to remaining compliant with IRS frameworks.
Taxable Events: When Selling and Disposing of Crypto Matters
Since the IRS classified virtual currencies as property rather than traditional currency in 2014, any disposal of a digital asset requires strict tracking. A taxable event occurs whenever you sell, exchange, or use crypto for goods or services. Simply holding a digital asset in your personal wallet—even if it appreciates significantly in value—does not trigger a tax liability until a disposal takes place.
Common scenarios that trigger a taxable realization event include:
- Selling cryptocurrency for fiat currency (such as USD or EUR).
- Exchanging one cryptocurrency for another digital asset, such as swapping Ethereum for a decentralized finance token.
- Using digital assets to purchase everyday items, such as buying a cup of coffee with Bitcoin.
- Spending native tokens like Ether (ETH) to pay for transaction fees, commonly referred to as "gas".
Conversely, moving digital assets between your own personal wallets or selling crypto at a loss generally does not generate an immediate tax liability. Instead, realized losses can be strategically applied to offset gains made elsewhere in your portfolio.
Short-Term vs. Long-Term Capital Gains
The length of time you hold a digital asset before executing a sale dictates how your profits are taxed. The IRS categorizes crypto holdings into two distinct periods:
| Holding Period | Tax Classification | Applicable Federal Rates |
|---|---|---|
| One year or less | Ordinary Income | 10% to 37% |
| More than one year | Capital Gains | 0%, 15%, or 20% (+ potential 3.8% NIIT) |
To calculate your exact capital gain or loss, you must determine your cost basis. This is calculated by taking the original price you paid for the asset plus any associated acquisition fees, and subtracting that figure from the final sale price. Only the resulting difference is subject to taxation.
Reporting Requirements and Tax Lots
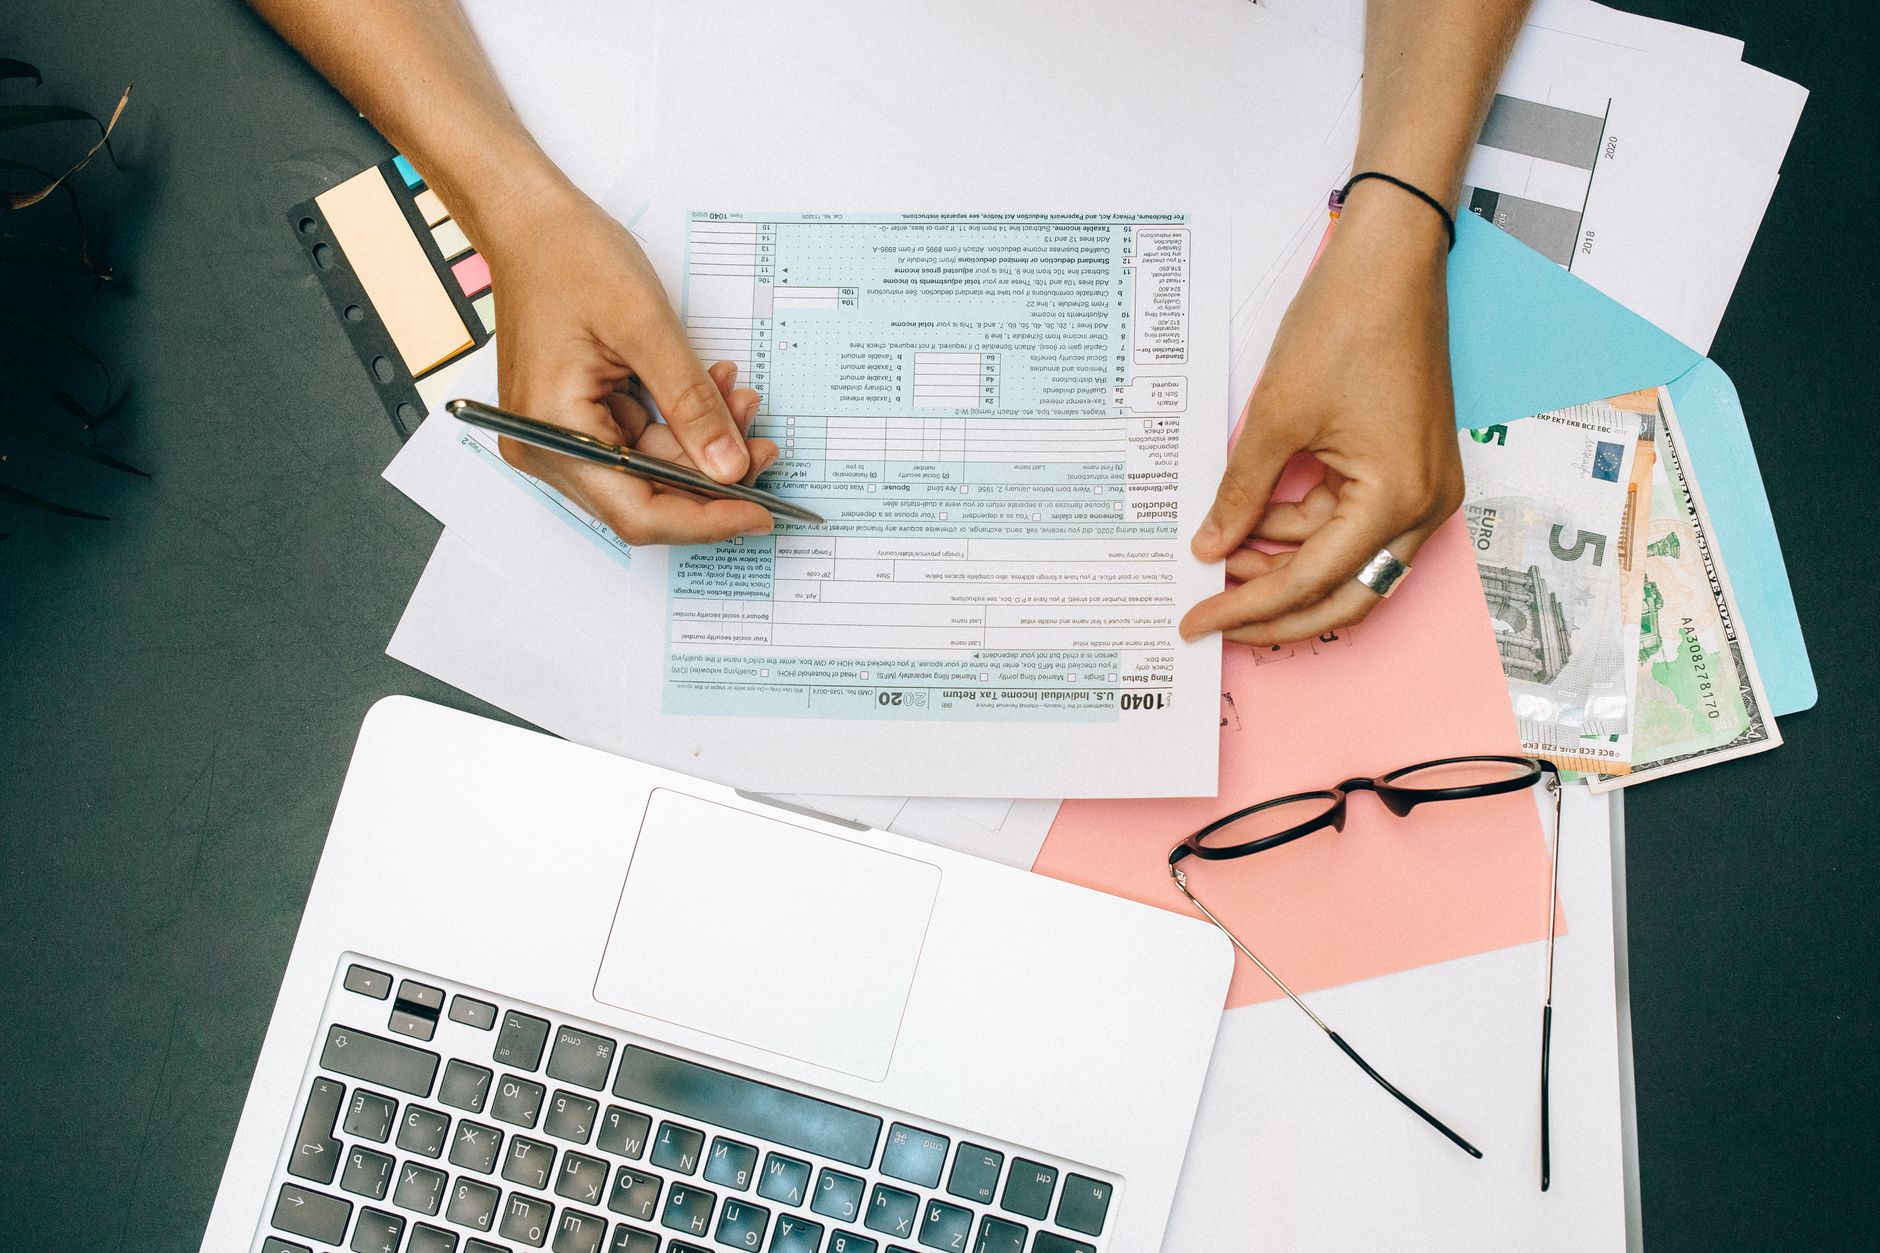
Tax compliance requires meticulous record-keeping. Under federal tax guidelines, realized capital gains and losses must be reported on Schedule D of Form 1040. Furthermore, the IRS requires centralized brokers and exchanges to report user transactions directly via Form 1099-DA, providing both the trader and the agency with exact purchase and sale data.
Platforms that support crypto tax lots allow users to track specific units of a digital asset based on acquisition dates and individual cost bases. Managing specific tax lots during a sale allows investors to optimize their tax strategy, though this feature is typically restricted to coin-based orders rather than dollar-based orders or stablecoin trades.
Frequently Asked Questions
Do I have to pay taxes if I sell my crypto for another cryptocurrency?
Yes, in most jurisdictions including the United States, swapping one cryptocurrency for another is considered a disposal event. This means it triggers a capital gain or loss that must be calculated and reported. An exception to this rule is France, which only taxes crypto when it is converted back into fiat currency.
How does the IRS know about my crypto transactions?
The IRS tracks digital asset activity through multiple channels, including mandatory broker reporting on Form 1099-DA. Crypto brokers are required to send copies of this form detailing purchases and sales to both you and the IRS.
Can I use crypto losses to lower my overall tax bill?
Yes, if you sell cryptocurrency for less than you acquired it for, you generate a capital loss. You can use these capital losses to offset capital gains realized elsewhere in your portfolio, reducing your overall taxable liability.
References & Sources
- Crypto Tax Guide: 2026 Rates and Rules - NerdWallet
- Selling Crypto: Do you Pay Taxes On Bitcoin Sales? | Koinly
- Taxing Crypto | Cato at Liberty Blog
- Crypto tax lots | Robinhood
- Crypto tax lots | Robinhood
Editorial Note: This article was researched via verified live web sources and published on 2026-11-02. Questions or feedback? Contact the editorial staff at TrendsInNews.
Photo credit: Tara Winstead / Pexels